Quick answer
Ballarat business owners use property-secured loans to fund construction and trades, manufacturing, hospitality, agriculture-linked businesses and property purchases. Loans run from $20,000 to $5,000,000 as first mortgages, second mortgages or caveats over homes, heritage buildings, commercial and rural property, assessed on Ballarat sales evidence, with Victorian titles and duty, and no valuation needed before approval.
Key points
- Lending across Ballarat, its growth corridors and the Central Highlands
- Heritage commercial buildings, homes and industrial property considered
- Construction, manufacturing, hospitality and agribusiness commonly funded
- Victorian land transfer duty administered by the State Revenue Office
- Interest prepaid or added to the loan
A goldfields city that keeps growing
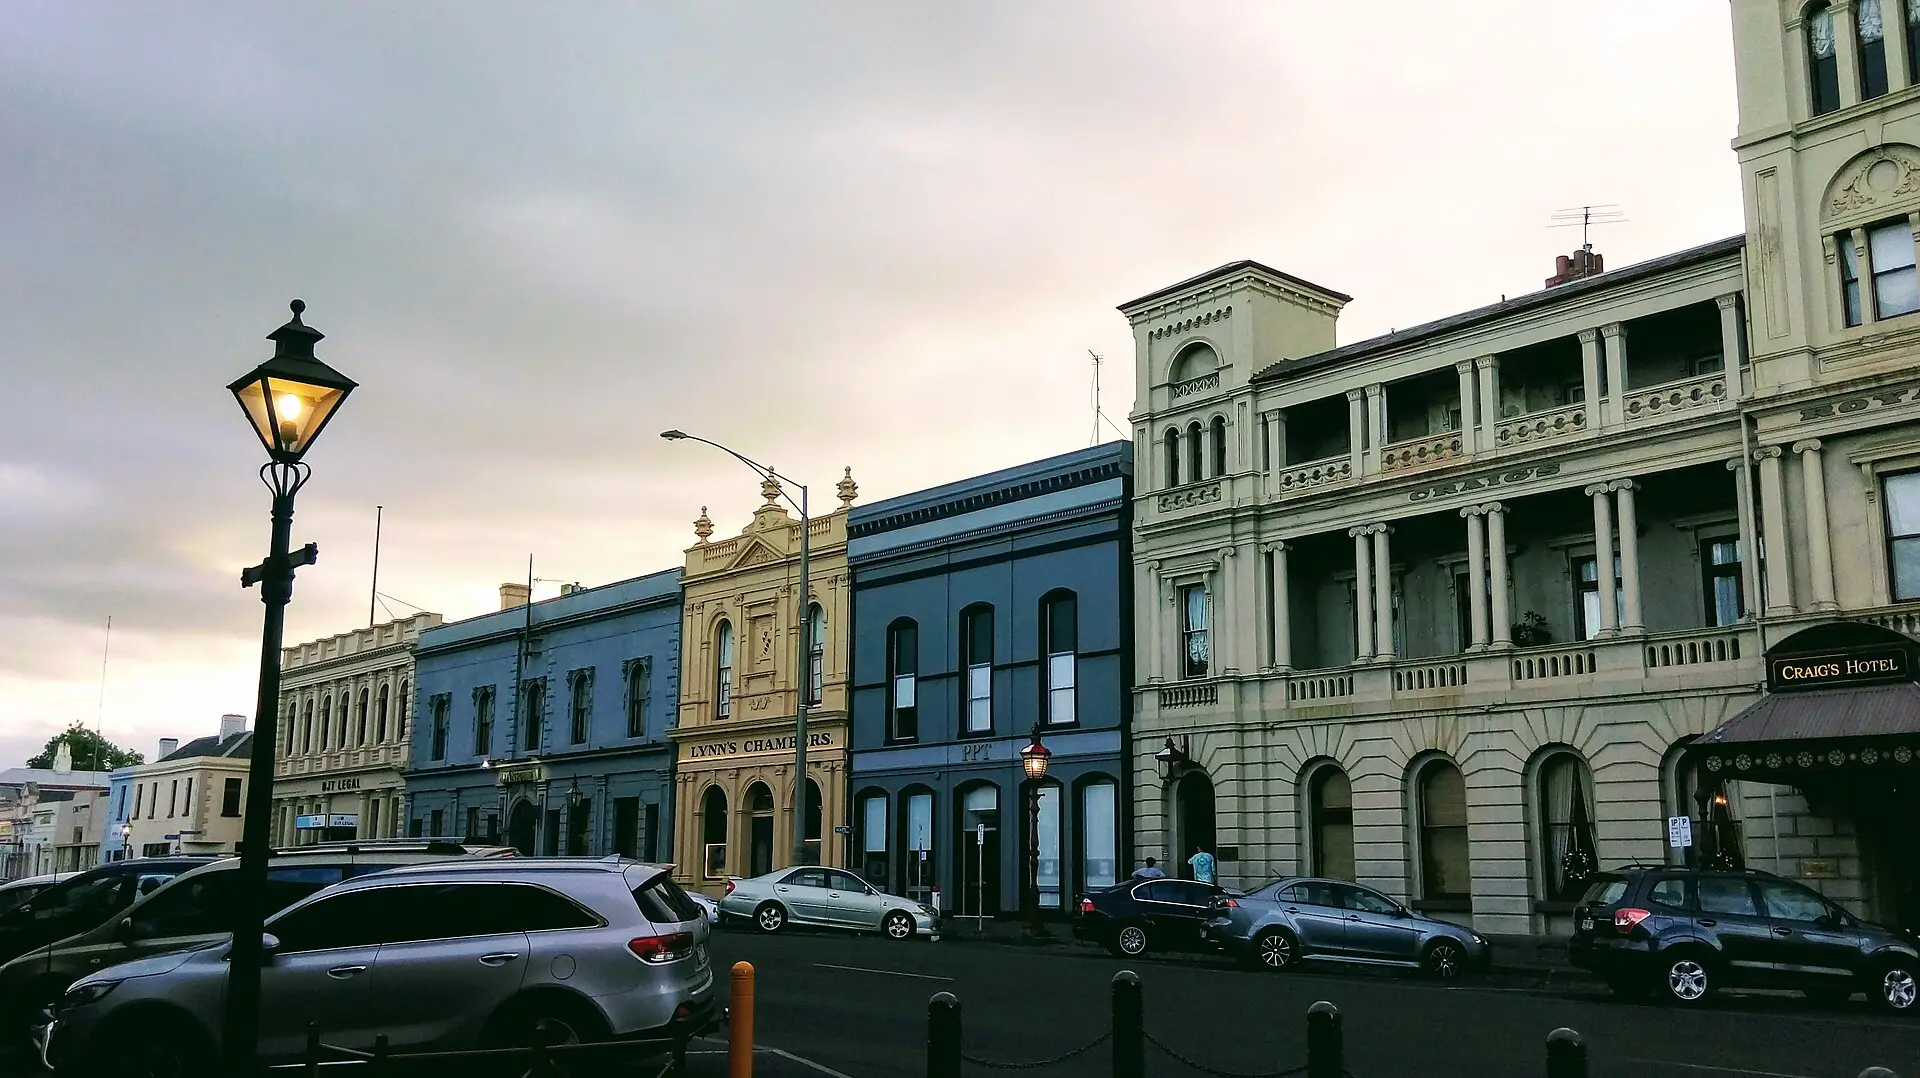
Ballarat grew from the gold rush into one of Victoria’s largest inland cities, and its grand Victorian streetscapes still define the centre. Today its economy rests on health, education, government services, manufacturing, construction, tourism and the agricultural region around it. Rail links to Melbourne have brought steady population growth, and with it demand for housing, services and trades. Many local business owners have built equity in homes and commercial buildings that they can use to fund their businesses.
How Ballarat businesses use secured finance
- Construction and trades. Bridging progress claims in the city’s growth areas. See construction.
- Manufacturing. Materials and labour for large orders from regional and national customers.
- Hospitality and tourism. Refurbishing venues in heritage buildings and carrying businesses through winter.
- Agribusiness and rural services. Seasonal inputs and stock for businesses serving the farming region.
- Property purchases. Buying heritage shops, offices or industrial units.
- Tax debt. Clearing ATO arrears before firmer action.
The Ballarat property market
The city centre is full of heritage commercial buildings along Sturt and Lydiard streets, with shops and offices on the ground floor and sometimes residential above. Established suburbs such as Lake Wendouree, Soldiers Hill and Mount Clear have character homes with steady demand. Growth areas in Ballarat West, Lucas, Alfredton and to the north have large numbers of new homes. Industrial land at Wendouree and Delacombe supports manufacturing and trade businesses. Rural and lifestyle properties surround the city. Each is assessed on recent Ballarat evidence, and no valuation is needed before approval. Our guide to regional property as security explains how regional markets are assessed.
See what your Ballarat property can support with a short enquiry.
Victorian specifics
Land transfer duty is administered by the State Revenue Office Victoria, and titles are registered with the Victorian land registry. Heritage overlays apply to much of central Ballarat and can affect redevelopment plans, which matters for land and development loans more than for loans against existing buildings. If you are buying or refinancing a heritage-listed shopfront in Lydiard or Sturt Street, mention the listing early so the lender can allow for it.
An illustrative Ballarat loan
Illustrative only. A family-owned joinery in Wendouree wins a contract to supply kitchens and cabinetry for a new aged-care facility, paid on milestones. Timber, hardware and extra staff are needed for months before the first payment. A first mortgage over the joinery’s factory, held in a family trust, funds the materials and wages, with interest capitalised. As milestones are paid, the loan is reduced and then cleared.
Commuters and Melbourne links
Many Ballarat residents work in or run businesses connected to Melbourne. A Ballarat home can be used to secure a loan for a Melbourne-based business and vice versa, giving owners flexibility to choose the property with the most suitable equity.
Questions Ballarat owners ask
Do you lend in surrounding towns like Daylesford or Creswick? Yes, assessed on local sales evidence.
Can a mixed shop and residence in the centre be used? Yes, assessed on its combined use and local evidence.
Can a loan fund a heritage restoration? Yes, for business purposes, with the works plan and exit considered.
Mistakes to avoid
- underestimating restoration costs in heritage buildings
- relying on a single large customer
- using GST and PAYG withholding to fund materials
- assuming rural land will support the same LVR as a suburban home
Preparing your enquiry
Have the property address, a current mortgage statement, the amount needed and the expected repayment date ready. For heritage or rural property, photos and any recent reports are useful because no valuation is needed before approval and the assessment relies on the evidence available.
Health, education and the public sector
Ballarat’s hospitals, university campus and government offices are large employers, and they support a ring of smaller businesses: medical and allied health practices, cleaning and maintenance contractors, IT and professional services, catering and childcare. Many of these businesses work on monthly invoicing to institutional clients, which can create a lag between payroll and payment. A secured facility behind a home or business premises lets them take on larger contracts with confidence. As the contract matures and payments become regular, the loan can be reduced or refinanced into a conventional bank facility, leaving the business with a stronger trading record.
Ballarat property, local answers
From a Lydiard Street shopfront to a home in Lake Wendouree, each property is judged on its own facts. Share the address, the current debt, the amount and your repayment plan. Enquiring involves no credit check, and your details stay with one team, and accurate details help us respond quickly. Start a Ballarat enquiry.
Frequently asked questions
Can a heritage building in central Ballarat be used as security?
Yes. Heritage commercial buildings are assessed on their current use, condition, leases and local sales evidence, with any heritage controls considered.
Do you lend in Ballarat's growth areas?
Yes. Newer estates to the west and north are assessed on estate-level sales evidence and nearby resales.
Can rural land near Ballarat secure a business loan?
Yes, case by case. Rural and lifestyle land may attract a more conservative LVR, and additional security can help.
How fast can a Ballarat loan settle?
On straightforward deals funds can be available in as little as 24 hours once documents are signed.
Prefer to start now? Enquire here
About 60 seconds. No credit check when you first enquire, and a secured lending specialist calls you back.