Quick answer
Central Coast business owners use property-secured loans to fund construction and trades, retail and hospitality, health practices, property purchases and tax debt clearance, often using equity built up in coastal and lakeside homes. Loans run from $20,000 to $5,000,000 as first mortgages, second mortgages or caveats, with NSW titles and duty, and no valuation needed before approval.
Key points
- Lending across Gosford, Terrigal, The Entrance, Wyong, Tuggerah and the peninsula
- Many owners hold strong equity in coastal and lakeside homes
- Trades, construction, retail, hospitality and health businesses commonly funded
- Titles handled by NSW Land Registry Services
- Interest prepaid or added to the loan
Between Sydney and Newcastle
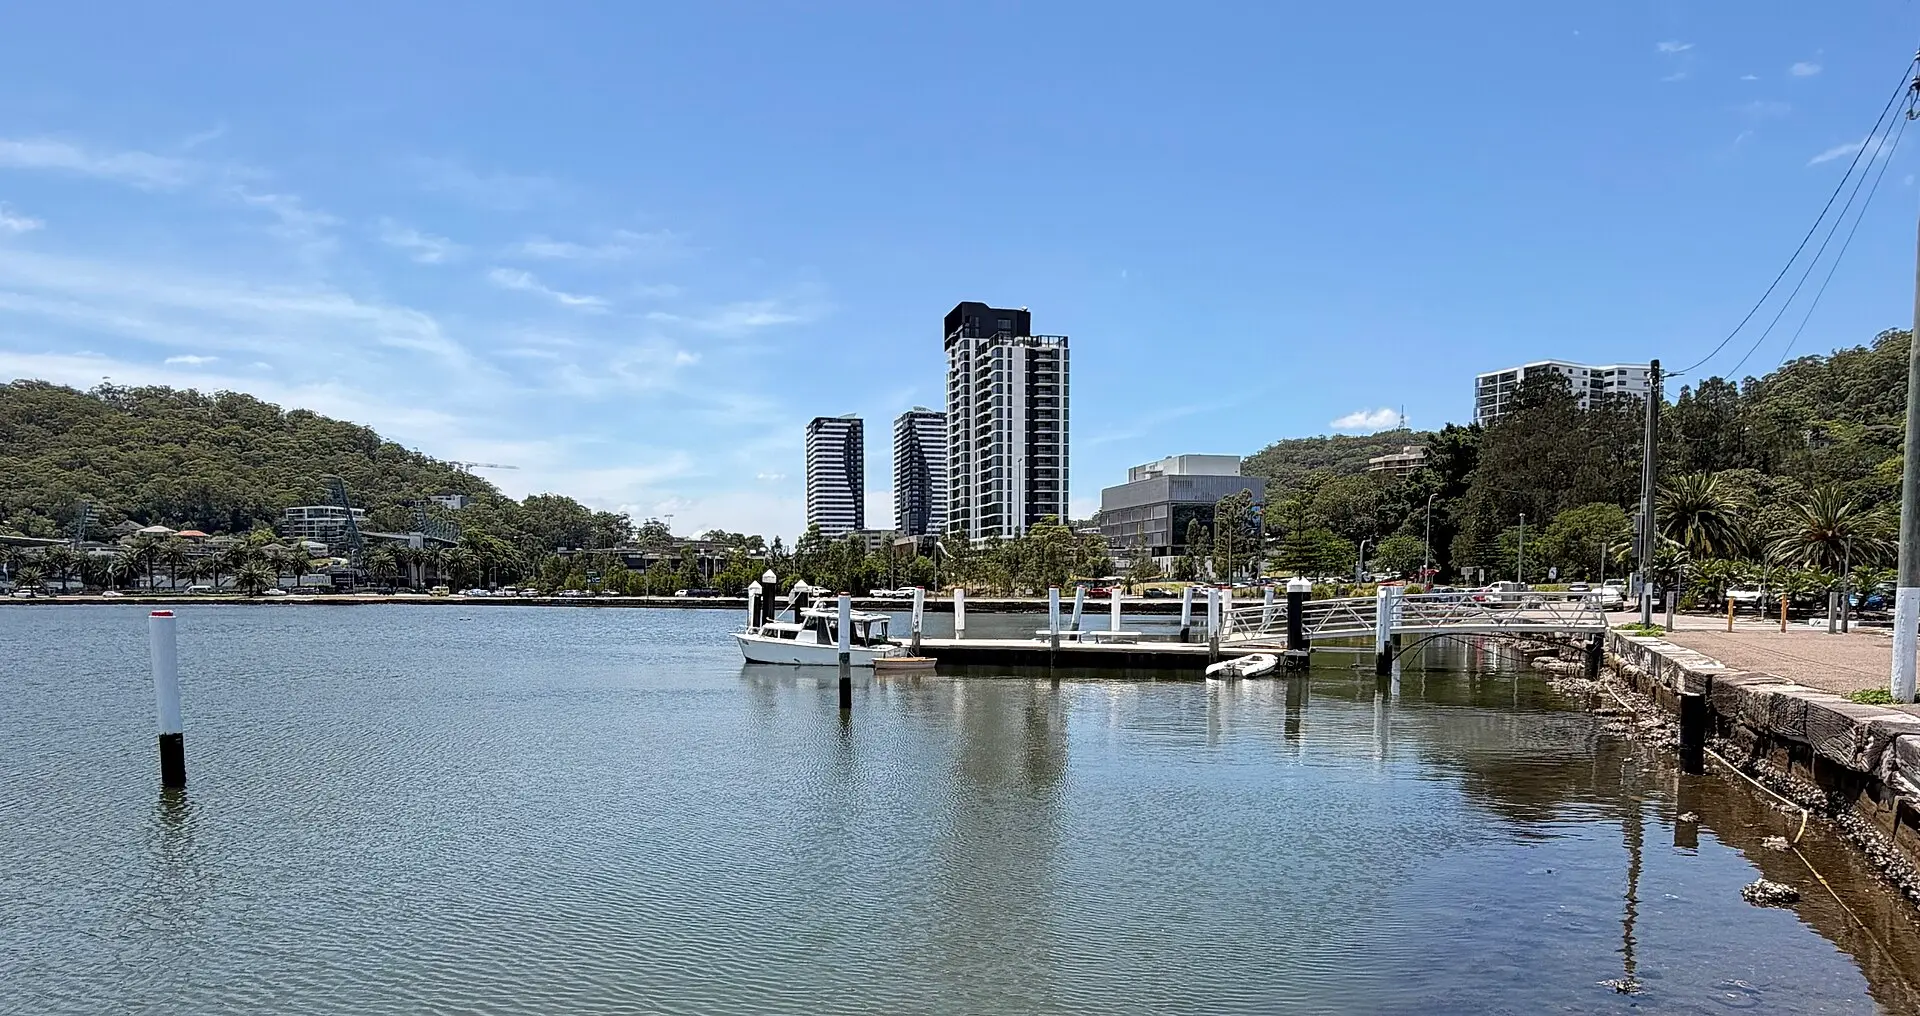
The Central Coast sits between Australia’s largest city and the Hunter, with a large population, a strong small-business sector and a growing commuter and work-from-home community. Construction, trades, retail, health care and tourism are major employers. Property values have risen as people move from Sydney, leaving many long-term owners with substantial equity in homes around the beaches, lakes and Brisbane Water.
How Central Coast businesses use secured finance
- Trades and construction. Bridging progress claims and retentions, and clearing BAS arrears. See trades.
- Retail and hospitality. Stock, refurbishments and seasonal cash flow in shopping centres, strips and tourist areas. See retail.
- Health practices. Buying rooms and funding fit-outs.
- Property purchases. Settling commercial and industrial purchases on time.
- Equity release. Funding a business through a second mortgage behind the family home.
The Central Coast property market
The region includes beachside suburbs such as Terrigal, Avoca, Copacabana and The Entrance, waterfront homes around Brisbane Water and Tuggerah Lake, the revitalising Gosford city centre with new apartment towers, established family suburbs, and industrial and commercial areas at West Gosford, Somersby, Tuggerah and Warnervale. Coastal and waterfront homes command premium prices; newer estates in the north are assessed on estate-level sales. Flood and coastal overlays are considered where relevant. No valuation is needed before approval.
See what your Central Coast property can support with a short enquiry.
NSW specifics
Central Coast property is recorded with NSW Land Registry Services, which is where a lender’s mortgage or caveat is lodged. Revenue NSW assesses duty on purchases. Development in the Gosford city centre and elsewhere runs through council and state planning processes.
Commuter-owned businesses
Many Central Coast owners run businesses in Sydney or work across both regions. The security does not need to be where the business trades. A Central Coast home can be used to secure a loan for a Sydney company, which is often simpler than using an inner-city property with a larger existing mortgage.
An illustrative Central Coast loan
Illustrative only. A roofing contractor based at West Gosford has grown quickly on residential work across the Coast and the Hunter. Several builders have extended payment terms, and the business has fallen a quarter behind on GST. The owner’s Terrigal home carries a modest bank loan. A second mortgage clears the ATO and funds two months of wages and materials, with interest capitalised. As builders pay, the owner repays the loan within the year.
Seasonal tourism on the coast
Beach towns see busy summers and quieter winters. Hospitality and accommodation businesses can borrow ahead of the quiet months, capitalise interest and repay from summer trade. A buffer in the term protects against a weaker season or wet weather.
Questions Central Coast owners ask
Can a unit in the new Gosford towers secure a loan? Yes, assessed on the building and resale evidence.
Do bushfire overlays matter? They are considered as part of the property assessment and insurance.
How quickly can funds arrive? On straightforward deals, in as little as 24 hours once documents are signed.
Mistakes to avoid
- using tax money to cover wages during a busy period
- relying on summer trade without a buffer
- assuming waterfront property will be valued without considering overlays
- leaving funding until a supplier issues a statutory demand
Gosford’s renewal and commercial property
The Gosford city centre has seen significant investment in new apartments, offices and public buildings, with more planned. Commercial property in the centre and in business parks at West Gosford, Erina and Tuggerah is used by professional firms, health practices and retailers. Practitioners buying their rooms, or retailers buying the shop they trade from, often use a private loan to settle quickly and refinance with a bank once the purchase is complete.
Industry at Somersby and the north
Somersby, Tuggerah and the Warnervale area host manufacturing, food processing, distribution and trade businesses. Industrial property in these estates is generally regarded as solid security, and businesses that own their premises through a family trust can use them to fund expansion or a large order. Where the premises already carry a bank loan, a second mortgage can sit behind it.
Preparing your enquiry
A property address, a current mortgage statement, the amount needed and a realistic repayment date are the four details that matter most at the start.
Central Coast property, honest answers
From a lakeside home to a Somersby factory, every property is assessed on its own merits. Give us the basics: where the property is, what it owes, how much you need and how the loan ends. We run no credit check at enquiry stage, and your details stay with our team, and recent local sales help us give you a reliable answer. Start a Central Coast enquiry.
Frequently asked questions
Do you lend across the whole Central Coast?
Yes. From the Woy Woy peninsula and Gosford to Terrigal, The Entrance, Wyong and the northern lakes, each property is assessed on local evidence.
Can a Central Coast home be used to secure a loan for a Sydney business?
Yes. Many Central Coast residents run businesses in Sydney, and their homes can be used to secure business loans wherever the business operates.
Can waterfront property be used as security?
Yes. Waterfront homes are assessed on local sales evidence, with any flood or coastal overlays considered.
Do you lend to tradies on the Central Coast?
Yes. Trade businesses often use home equity to bridge slow-paying builders and clear tax arrears.
Prefer to start now? Enquire here
About 60 seconds. No credit check when you first enquire, and a secured lending specialist calls you back.