Quick answer
Launceston and northern Tasmanian business owners use property-secured loans to fund food and wine production, tourism and hospitality, construction and trades, agribusiness and property purchases. Loans run from $20,000 to $5,000,000 as first mortgages, second mortgages or caveats, assessed on local sales evidence, with titles handled by Tasmania's Land Titles Office and no valuation needed before approval.
Key points
- Lending across Launceston, the Tamar Valley, the north-west coast and the north-east
- Food, wine, tourism, construction and agribusiness commonly funded
- Heritage commercial buildings and homes considered
- Titles handled by the Land Titles Office, duty by the State Revenue Office
- Interest prepaid or added to the loan
Northern Tasmania’s centre
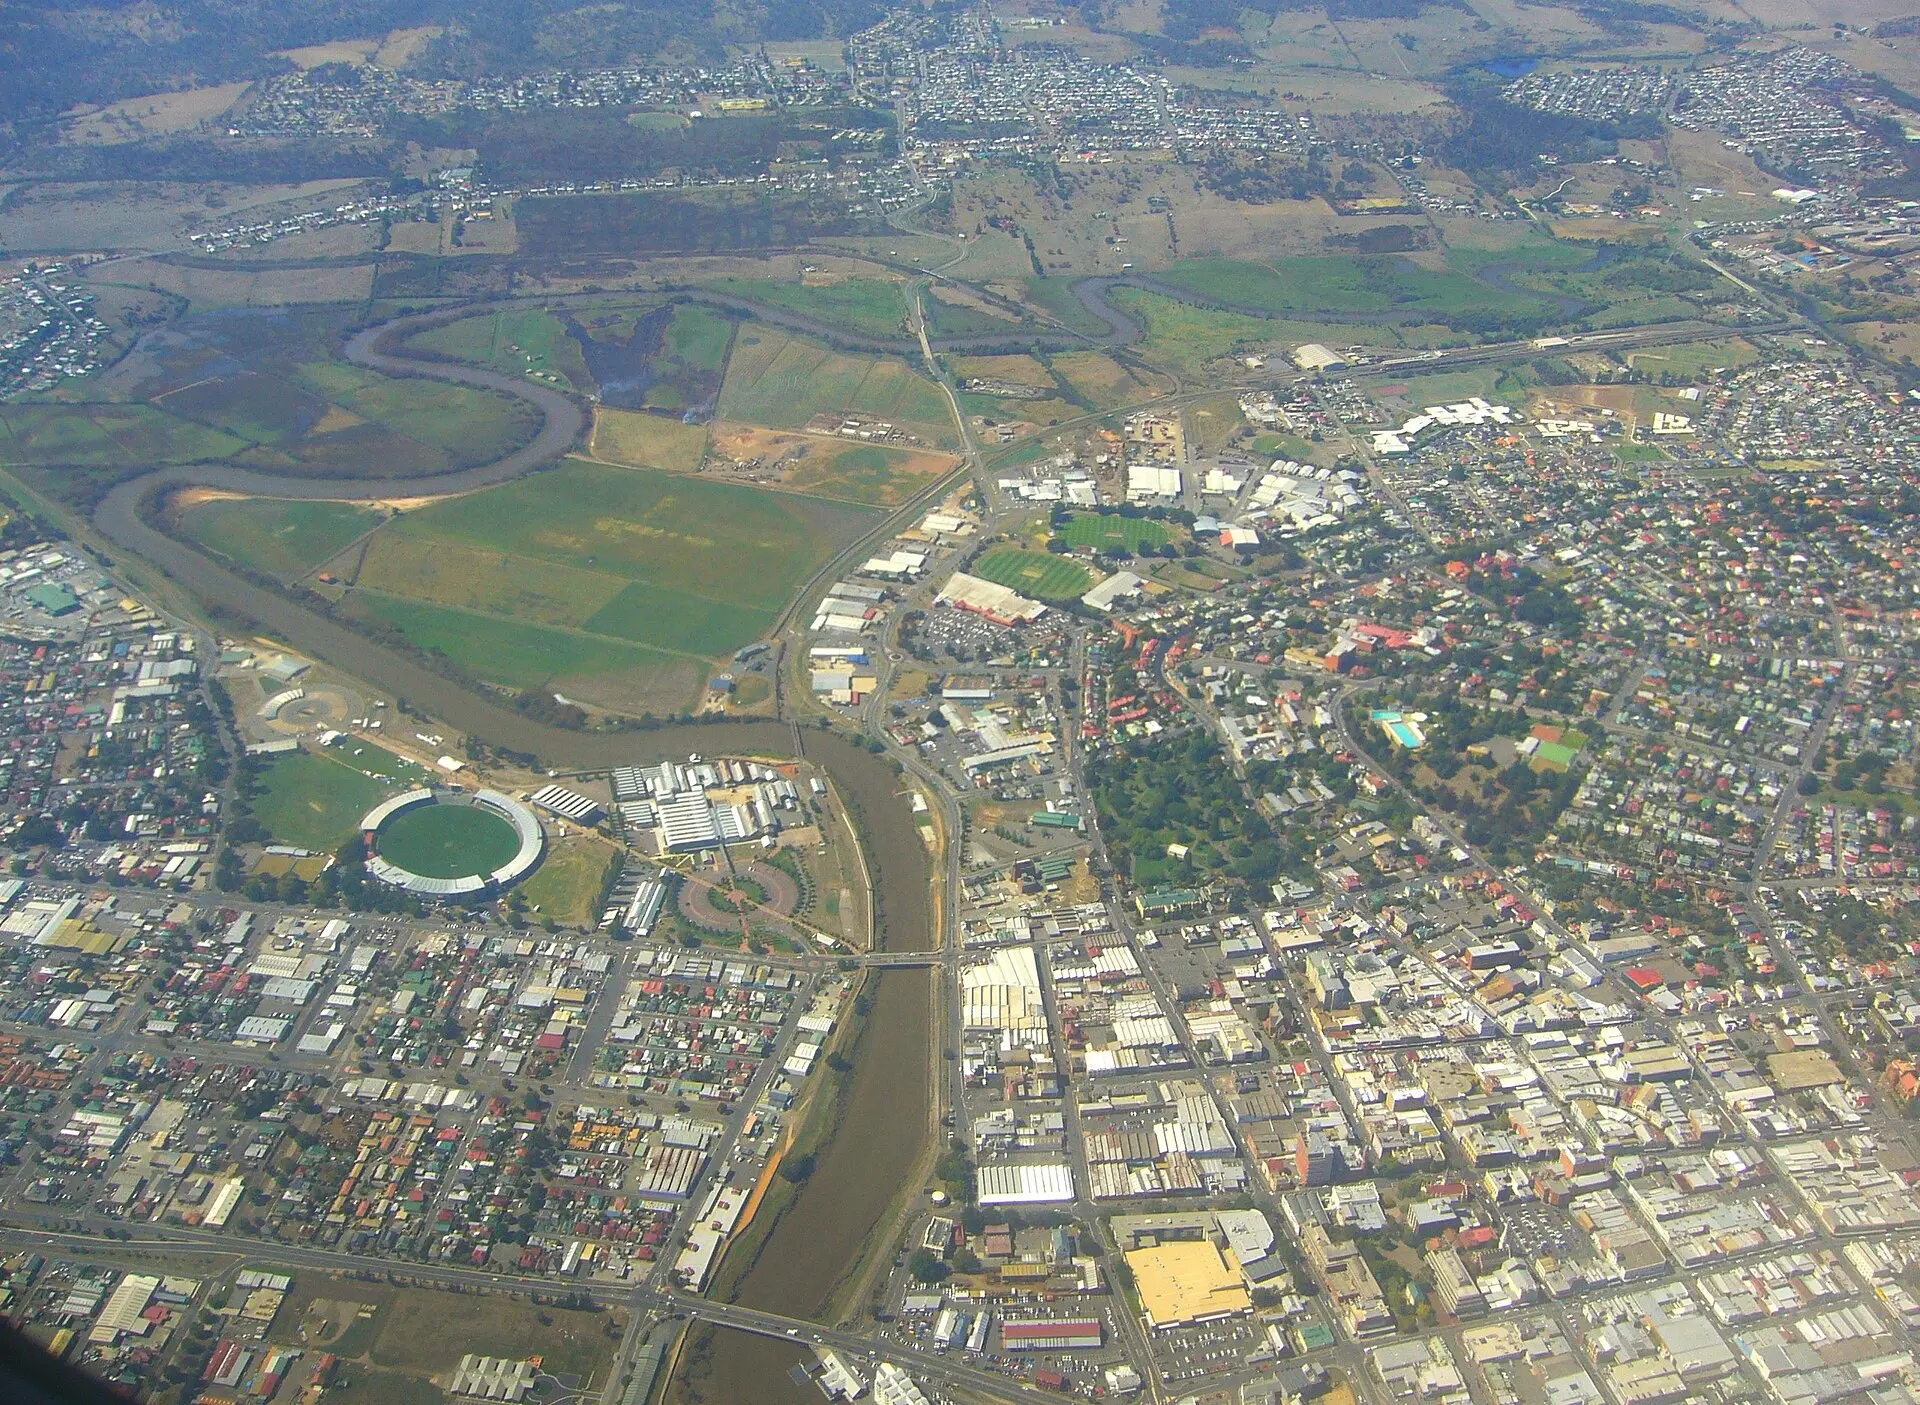
Launceston, at the head of the Tamar River, is the commercial centre of northern Tasmania. Its economy includes health, education, government services, manufacturing, construction and a strong food, wine and tourism sector built on the Tamar Valley and the surrounding regions. Agriculture across the north and north-west supplies dairy, vegetables, beef and specialty produce. Many businesses are family-owned and many owners hold property with substantial equity.
How Launceston businesses use secured finance
- Food and wine. Funding vintage costs, processing equipment and stock carried until sale.
- Tourism and hospitality. Refurbishing venues and accommodation and carrying businesses through winter. See hospitality.
- Construction and trades. Bridging progress claims on residential and commercial projects.
- Agribusiness. Seasonal inputs and land purchases. See agriculture.
- Property purchases. Buying heritage shops, offices or industrial units.
- Tax debt. Clearing arrears with a second mortgage behind the family home.
The northern Tasmanian property market
Launceston’s centre has heritage commercial buildings and a compact CBD. Established suburbs such as East and West Launceston, Trevallyn and Newstead offer character homes, while newer housing has spread to areas such as Legana, Prospect Vale and Kings Meadows. Industrial land supports manufacturing and trade businesses, and the Tamar Valley and wider north offer vineyards, farms and lifestyle properties. The market is smaller than mainland capitals, so evidence for unusual properties can be thinner. No valuation is needed before approval. See our guide on regional property as security.
See what your Launceston property can support with a short enquiry.
Tasmanian specifics
Northern Tasmanian property appears on the island’s title register, kept by the Land Titles Office in Hobart. Duty on purchases is collected by Tasmania’s State Revenue Office.
Food, wine and long production cycles
Wineries, distilleries and food producers often carry costs for months or years before products are sold. Secured loans with interest capitalised suit these cycles, repaid as product is sold or as a refinance becomes available. Lenders appreciate a clear explanation of the production timeline and sales channels.
An illustrative Launceston loan
Illustrative only. A Tamar Valley winery has strong demand for a new release but needs to fund barrels, bottling and a cellar door upgrade before the wine is ready for sale. The vineyard is specialised security, so the owners offer their home in Trevallyn alongside it. A loan secured over both funds the costs, with interest capitalised for eighteen months. As the release sells through the cellar door, restaurants and online, the owners repay the loan.
Questions Launceston owners ask
Do you lend in Devonport and Burnie? Yes, assessed on local evidence.
Can a heritage building in the CBD be used? Yes, assessed on use, condition and leases.
Can multiple properties secure one loan? Yes. Combining a home and a commercial or rural property is common.
Mistakes to avoid
- underestimating how long stock takes to sell
- relying on specialised property alone as security
- using tax money to fund production
- leaving funding until a supplier escalates
Preparing your enquiry
Note the address, the latest statement for any existing loan, what the funds are for and when you expect to repay. For producers, a short outline of the production and sales cycle helps a specialist set a realistic term.
Launceston’s growth and renewal
Launceston has seen renewed investment in its city centre, university campus and riverside precincts, and population growth from people relocating from interstate and other parts of Tasmania. That has supported construction and services businesses and lifted property values in many established suburbs. Long-term owners often have substantial equity behind modest bank loans, which can secure business borrowing without disturbing the existing mortgage.
The north-west coast and north-east
Beyond Launceston, Devonport, Burnie and Ulverstone support manufacturing, port activity, agriculture and tourism linked to the ferry and the coast, while the north-east has farming, forestry and growing tourism. Property in these areas can form part of the security, assessed on local sales evidence. Combining a coastal home with business premises or farmland is a common way to strengthen a deal.
Seasonal tourism in the north
Visitor numbers peak in summer, when the Tamar Valley’s cellar doors, restaurants and accommodation are busiest. Businesses that depend on visitors often borrow ahead of winter to keep staff and maintain properties, repaying from summer trade.
Northern Tasmanian property, careful answers
From a Trevallyn home to a Tamar Valley vineyard, each property is judged on its own facts. Describe the property, the debt on it, the amount and your exit. Northern Tasmanian enquiries carry no credit check at the first step, stay with our team, and clear details mean a quicker reply. Start a Launceston enquiry.
Frequently asked questions
Do you lend in the Tamar Valley and north-west coast?
Yes. Northern Tasmania is covered, including Devonport, Burnie and rural districts, each assessed on local sales evidence.
Can a vineyard or farm be used as security?
Yes, case by case. Vineyards and farms are specialised, so a home or other property is often added as security.
Can a Launceston property secure a loan for a business on the mainland?
Yes. The property and the business can be in different states, provided the loan is for business purposes.
How quickly can a loan settle?
On straightforward deals funds can be available in as little as 24 hours once documents are signed and returned.
Prefer to start now? Enquire here
About 60 seconds. No credit check when you first enquire, and a secured lending specialist calls you back.