Quick answer
Businesses in Parramatta and Western Sydney use property-secured loans to fund logistics and industrial growth, construction and trades, retail and hospitality, property purchases and tax debt clearance. Loans run from $20,000 to $5,000,000 as first mortgages, second mortgages or caveats over homes, units, warehouses and commercial property, with NSW titles and no valuation needed before approval.
Key points
- Lending across Parramatta, Blacktown, Penrith, Liverpool, Campbelltown and the Hills
- Logistics, industrial, construction and family businesses commonly funded
- Growth around the new airport and employment lands
- Titles handled by NSW Land Registry Services
- Interest prepaid or added to the loan
Sydney’s second CBD and its growth corridor
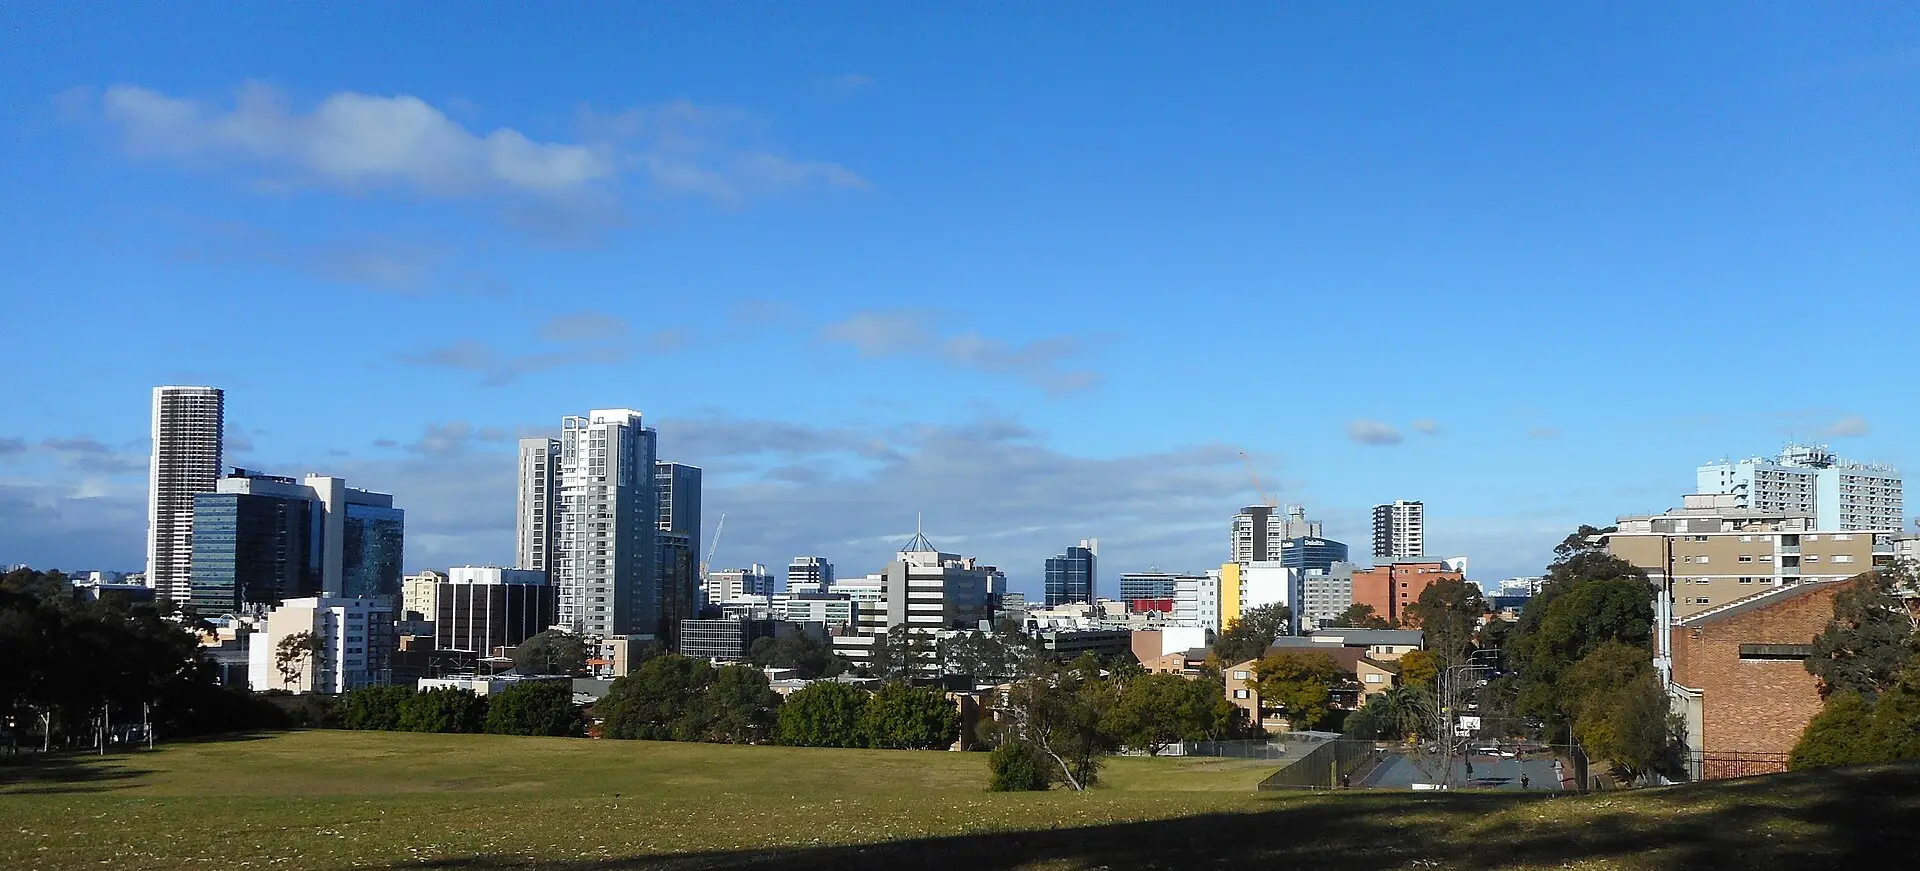
Parramatta has grown into a major commercial centre, and Western Sydney as a whole is one of the fastest-growing regions in Australia. New infrastructure, including the Western Sydney International Airport and surrounding employment lands, metro lines and motorways, has drawn logistics, manufacturing and service businesses, while new housing estates continue to expand in the north-west and south-west. Many of the region’s businesses are family-owned, and many owners hold significant equity in homes and commercial property.
How Western Sydney businesses use secured finance
- Logistics and warehousing. Buying or expanding warehouses, funding fleet deposits and carrying long customer payment terms. See transport and logistics.
- Construction and trades. Bridging progress claims on the region’s heavy pipeline of residential and infrastructure work. See construction.
- Retail and hospitality. Fit-outs, stock and refurbishments in busy town centres.
- Commercial property. Buying offices, shops and industrial units. See commercial property loans.
- Tax debt. Clearing ATO arrears with a second mortgage behind the family home.
The Western Sydney property market
The region is diverse. Parramatta’s centre has office towers and high-rise apartments. Established suburbs such as Baulkham Hills, Castle Hill, Epping and Strathfield have long-held family homes with substantial equity. Growth areas around Marsden Park, Box Hill, Oran Park and Leppington have large new estates. Industrial precincts at Wetherill Park, Smithfield, Eastern Creek, Erskine Park and around the new airport serve logistics and manufacturing. Each sub-market is assessed on its own evidence, and no valuation is needed before approval.
See what your Western Sydney property can support with a short enquiry.
Industrial land and the airport precinct
Industrial property in Western Sydney has been in strong demand from logistics and manufacturing businesses. Owners of well-located warehouses and yards often hold substantial equity that can secure a first mortgage for expansion or working capital. Land in the employment zones around the new airport is a developing market; lenders assess it on zoning, servicing and current evidence rather than future expectations.
Family businesses and structures
Many Western Sydney businesses are run by families through companies and trusts, with property held by individuals or related entities. That is entirely workable: the business borrows, and the property owners provide security and guarantees. A simple outline of who owns what makes the process faster.
An illustrative Western Sydney loan
Illustrative only. A family-owned freight business in Wetherill Park wins a contract with a national retailer that pays forty-five days after month end. The contract needs more trucks and drivers immediately. A first mortgage over the family’s warehouse, held in a related trust, funds the vehicle deposits and the first three months of wages and fuel, with interest capitalised. As payments arrive, the business repays part of the loan, and refinances the balance with its bank after a year of trading under the contract.
NSW specifics
Western Sydney security is registered on the NSW title system through NSW Land Registry Services, and Revenue NSW collects duty on property purchases. Planning for development sites in growth areas runs through local councils and the NSW Planning Portal, and some precincts have specific state planning controls.
Questions Western Sydney owners ask
Can a property in a new release area secure a loan before an established resale history exists? Yes, assessed on the best available evidence, which may include nearby estates.
Can the loan pay an interstate supplier? Yes. Funds can be paid wherever the business needs them.
Can I settle a warehouse purchase quickly? Yes. A private loan can settle on a vendor’s timetable, with a bank refinance later.
Mistakes to avoid
- growing a fleet or headcount faster than working capital allows
- using GST and PAYG withholding to fund growth
- relying on one large customer
- assuming land near the airport will be valued on future plans
Preparing your enquiry
Have the property address, a current mortgage statement, a short description of the need and the expected repayment date ready. For family groups, add a one-line note on which entity owns each property and which entity runs the business. If the deal involves buying a warehouse or shop, include the contract date and settlement date so the timeline can be planned backwards from settlement.
Western Sydney property, real answers
From a Parramatta apartment to an Eastern Creek warehouse, every property is assessed on its own merits. Start with the property, the balance owing, the figure you need and your way out of the loan. You face no credit check at this point, and your details stay with one team, and a summary of your structure helps us move quickly. Start a Western Sydney enquiry.
Frequently asked questions
Do you lend across all of Western Sydney?
Yes. From Parramatta and the Hills to Penrith, Liverpool and Campbelltown, each property is assessed on its own local sales evidence.
Can a warehouse in Western Sydney secure a business loan?
Yes. Industrial property in the region's established and newer estates is commonly used as first mortgage security.
Can I use a home in a new estate as security?
Yes. Homes in newer estates are assessed on recent resales within the estate and nearby suburbs.
Do you lend to family businesses with complex structures?
Yes. Companies, trusts and partnerships can borrow, with related parties providing security where needed.
Prefer to start now? Enquire here
About 60 seconds. No credit check when you first enquire, and a secured lending specialist calls you back.