Quick answer
Cairns and Far North Queensland business owners use property-secured loans to carry tourism businesses through seasonal swings, fund hospitality refurbishments, bridge construction progress claims, support agribusiness and buy property. Loans run from $20,000 to $5,000,000 as first mortgages, second mortgages or caveats, assessed on local evidence, with titles handled by Titles Queensland and no valuation before approval.
Key points
- Lending across Cairns, the northern beaches, the Tablelands and Port Douglas
- Tourism, hospitality, marine, construction and agribusiness commonly funded
- Wet season and visitor cycles built into loan terms
- Cyclone and flood considerations included in the assessment
- Interest prepaid or added to the loan
Gateway to the reef and the rainforest
Cairns is the hub of Far North Queensland and one of Australia’s best-known tourism destinations, with the Great Barrier Reef and the Wet Tropics on its doorstep. Tourism, hospitality and marine businesses dominate, alongside health, education, construction, aviation and the agricultural districts of the Tablelands and coast. The region’s economy moves with visitor numbers, seasons and international travel trends, which makes cash flow planning essential.
How Cairns businesses use secured finance
- Tourism and hospitality. Carrying businesses through the wet season and funding refurbishments before the dry. See hospitality.
- Marine and tour operators. Funding vessel refits, deposits and working capital.
- Construction and trades. Bridging progress claims on residential, resort and commercial projects.
- Agribusiness. Seasonal inputs for sugar, bananas, avocados and other crops. See agriculture.
- Property purchases. Buying commercial premises or accommodation businesses.
- Tax debt. Clearing arrears after a slow season.
The Cairns property market
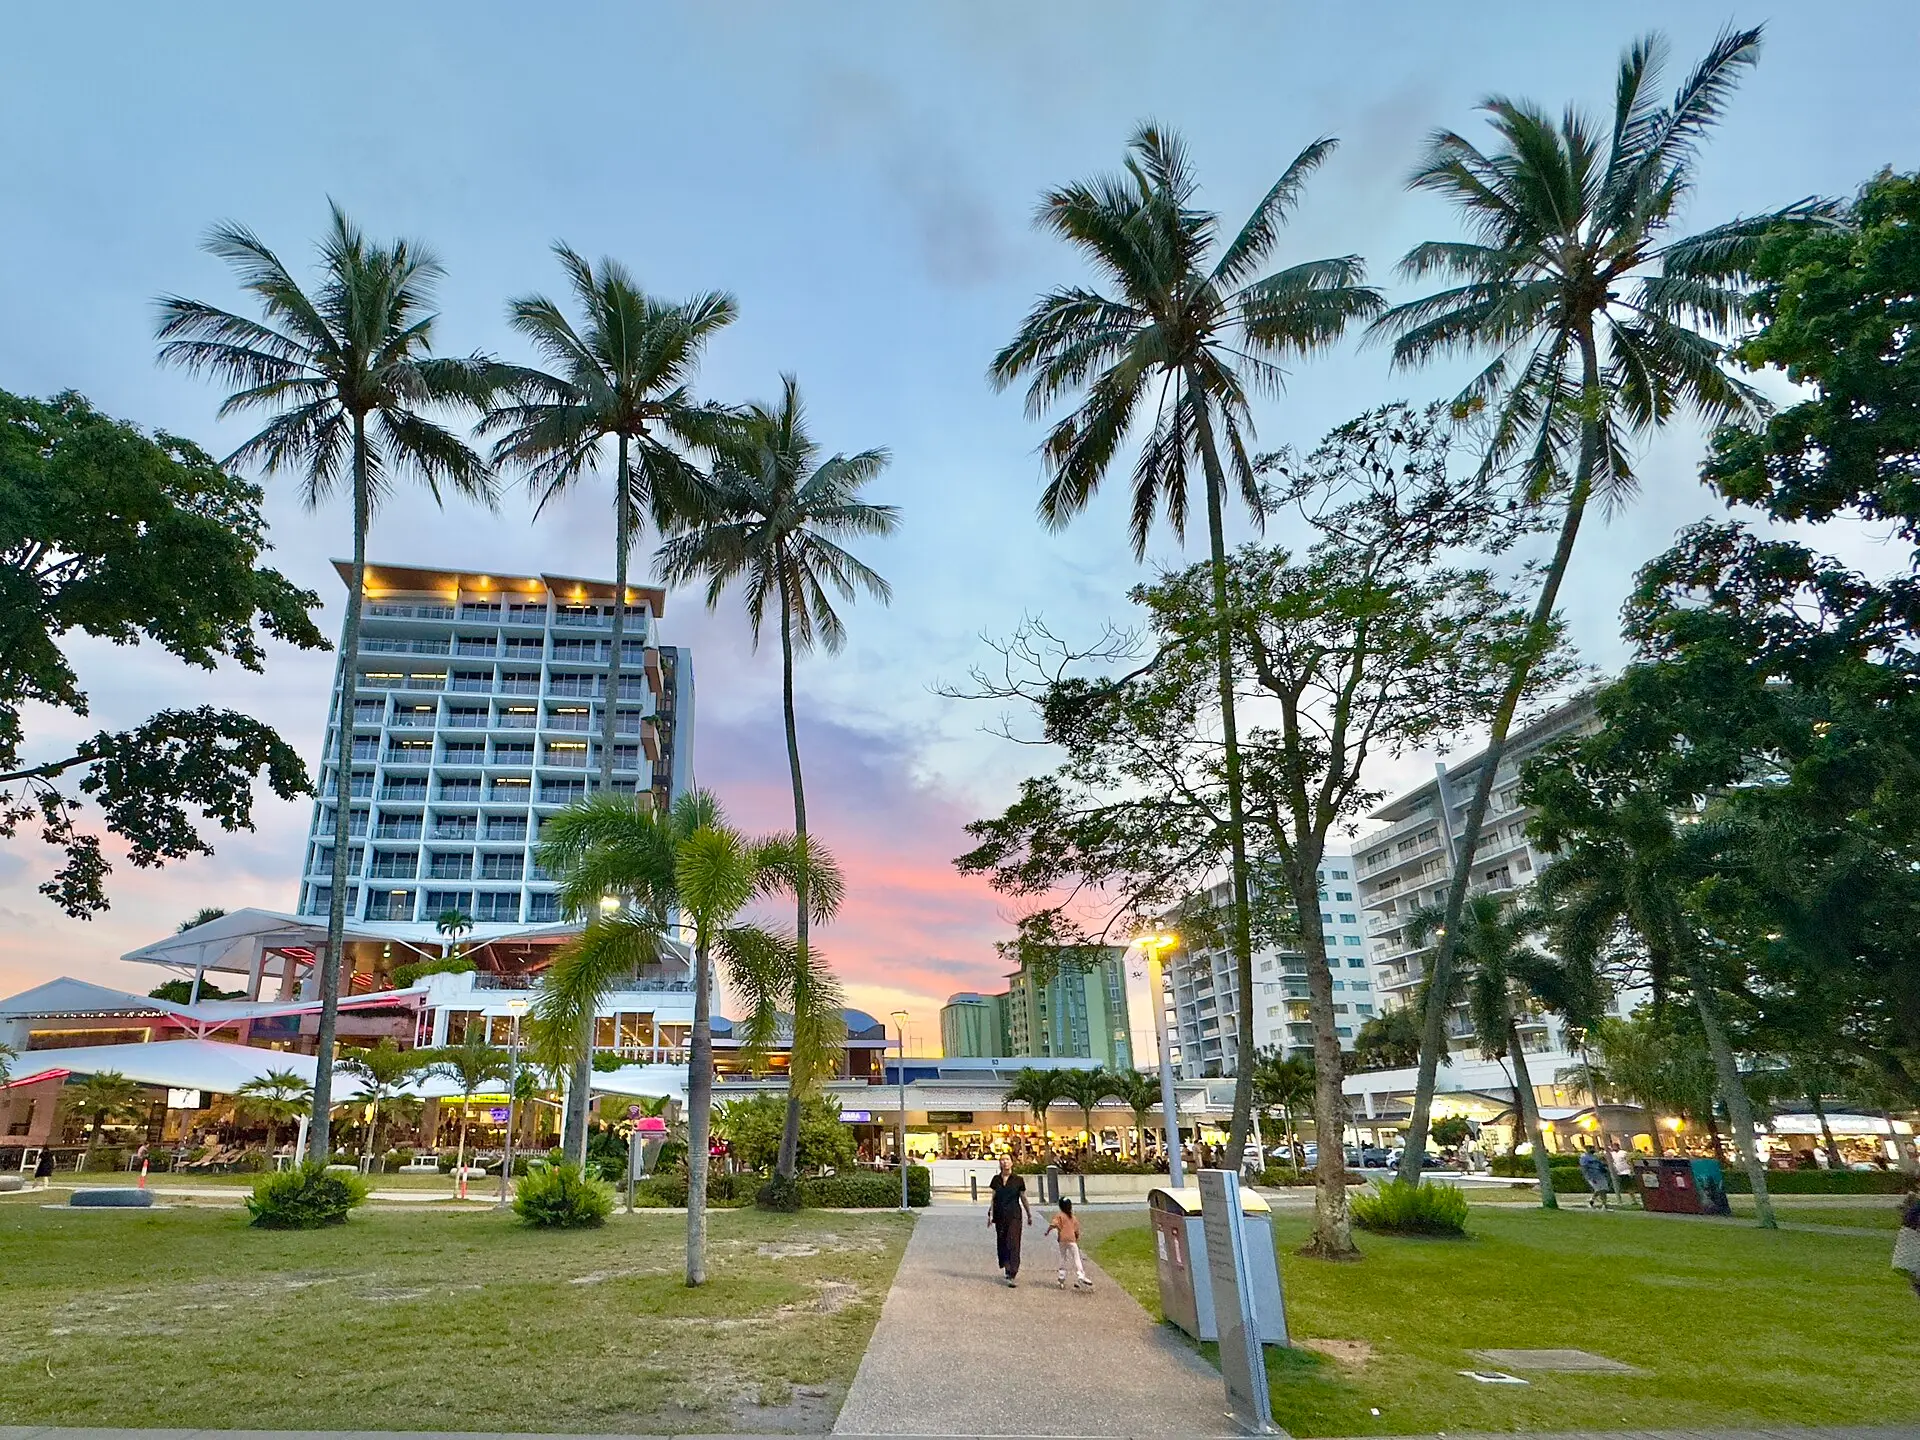
The region includes city-fringe suburbs such as Edge Hill and Whitfield, the northern beaches from Machans Beach to Palm Cove, growth areas to the south, apartments and holiday units along the Esplanade, resort towns such as Port Douglas, and farmland and lifestyle properties on the Tablelands. Short-stay and holiday properties are common. Each is assessed on its own recent sales evidence, and no valuation is needed before approval. Cyclone, flood and insurance considerations are part of every assessment.
See what your Cairns property can support with a short enquiry.
Queensland specifics
In Far North Queensland, as across the state, Titles Queensland keeps the register that records ownership, mortgages and caveats. The Queensland Revenue Office sets and collects transfer duty, so check its current concessions before buying commercial or rural property around Cairns.
Planning around the tourism year
Most Cairns tourism businesses earn the bulk of their revenue in the dry season, roughly the middle of the year, with quieter months during the wet. Borrowing before the quiet period, capitalising interest and repaying from peak trade suits that pattern. Build a buffer for events outside your control, such as weather or changes in international travel. Our guide on seasonal cash flow covers the planning in detail.
An illustrative Cairns loan
Illustrative only. A family-owned reef tour company needs a major refit for one of its vessels before the dry season. The work will take two months during the wet, when bookings are low. A second mortgage over the owners’ home in Redlynch funds the refit and two months of core staff wages, with interest capitalised. A strong dry season allows the owners to repay the loan by the end of the year.
Questions Cairns owners ask
Can a resort or accommodation business be financed? Accommodation property is specialised; it is assessed case by case and often combined with other security.
Do you lend in Port Douglas? Yes, assessed on local evidence.
Can a Cairns property secure a loan for a business in Brisbane? Yes. The security and the business can be in different places.
Mistakes to avoid
- relying on peak-season trading without a buffer
- refitting or refurbishing without funding the closed period
- underestimating insurance costs on security property
- using GST and PAYG withholding to cover wet-season wages
Preparing your enquiry
Have the property address, a current mortgage statement, insurance details, the purpose and your expected repayment date ready. For tourism businesses, last year’s monthly revenue helps a specialist set a term that fits the seasons.
Beyond tourism
Cairns has a broader economy than many visitors realise. The hospital and health precinct, the university campus, the airport and aviation maintenance, the marine industry servicing fishing, tourism and defence vessels, and construction all employ large numbers of people. Agricultural districts on the Tablelands and along the coast supply fruit, sugar, dairy and beef. Businesses supplying these sectors often work on monthly or milestone payments and can use property equity to bridge the timing.
Wet season construction
Construction work in the Far North slows during the wet, and projects can run late. Builders and trades should allow for weather delays when setting loan terms tied to progress claims, so a few lost weeks do not create pressure at the end of the term.
Holiday and short-stay property
Cairns, Palm Cove and Port Douglas have many holiday apartments and short-stay homes. These can be used as security, assessed as residential property on building quality and resale evidence, with their use noted.
Far North property, local understanding
From a Palm Cove apartment to a Tablelands farm, each property is judged on its own facts. Outline what you own, what it owes, what you need and how you will pay it back. We do no credit check on a first enquiry, it stays with one team, and seasonal trading figures help us respond with the right structure. Start a Cairns enquiry.
Frequently asked questions
Can a tourism operator borrow through the wet season?
Yes. A secured loan can carry a tourism or hospitality business through quieter months, repaid from the dry season's trade.
Do you lend on the Atherton Tablelands?
Yes, case by case, with farmland and lifestyle properties assessed on local evidence and often supported by additional security.
Can a holiday apartment be used as security?
Yes. Holiday and short-stay apartments are assessed as residential property on the building and recent resales.
How fast can a loan be arranged?
On straightforward deals funds can be available in as little as 24 hours once documents are signed.
Prefer to start now? Enquire here
About 60 seconds. No credit check when you first enquire, and a secured lending specialist calls you back.