Quick answer
Gold Coast business owners use property-secured loans to fund tourism and hospitality businesses, construction and development projects, property purchases and tax debt clearance. Loans run from $20,000 to $5,000,000 as first mortgages, second mortgages or caveats over homes, apartments and commercial property, with titles handled by Titles Queensland and no valuation needed before approval.
Key points
- Lending from Coomera to Coolangatta and the hinterland
- High-rise apartments, canal homes, commercial and industrial property considered
- Tourism, hospitality, construction and development commonly funded
- Titles Queensland handles registrations and caveats
- Funds in as little as 24 hours on straightforward deals
A city built on tourism, construction and property
The Gold Coast combines a large tourism and hospitality sector with one of Australia’s busiest construction and development markets. Population growth has driven demand for homes, apartments and commercial space, while tourism brings strong seasonal swings. Many business owners here hold substantial property equity, and secured lending lets them use it to fund growth, bridge seasonal gaps or keep projects moving.
How Gold Coast businesses use secured finance
- Development. Buying sites, holding through approvals and carrying unsold apartments or townhouses. See residual stock loans.
- Construction cash flow. Builders and trades bridging progress claims.
- Tourism and hospitality. Refurbishing venues and accommodation, and carrying businesses through quieter months. See hospitality.
- Property purchases. Settling commercial and investment purchases quickly.
- Tax debt. Clearing ATO arrears.
Gold Coast property as security
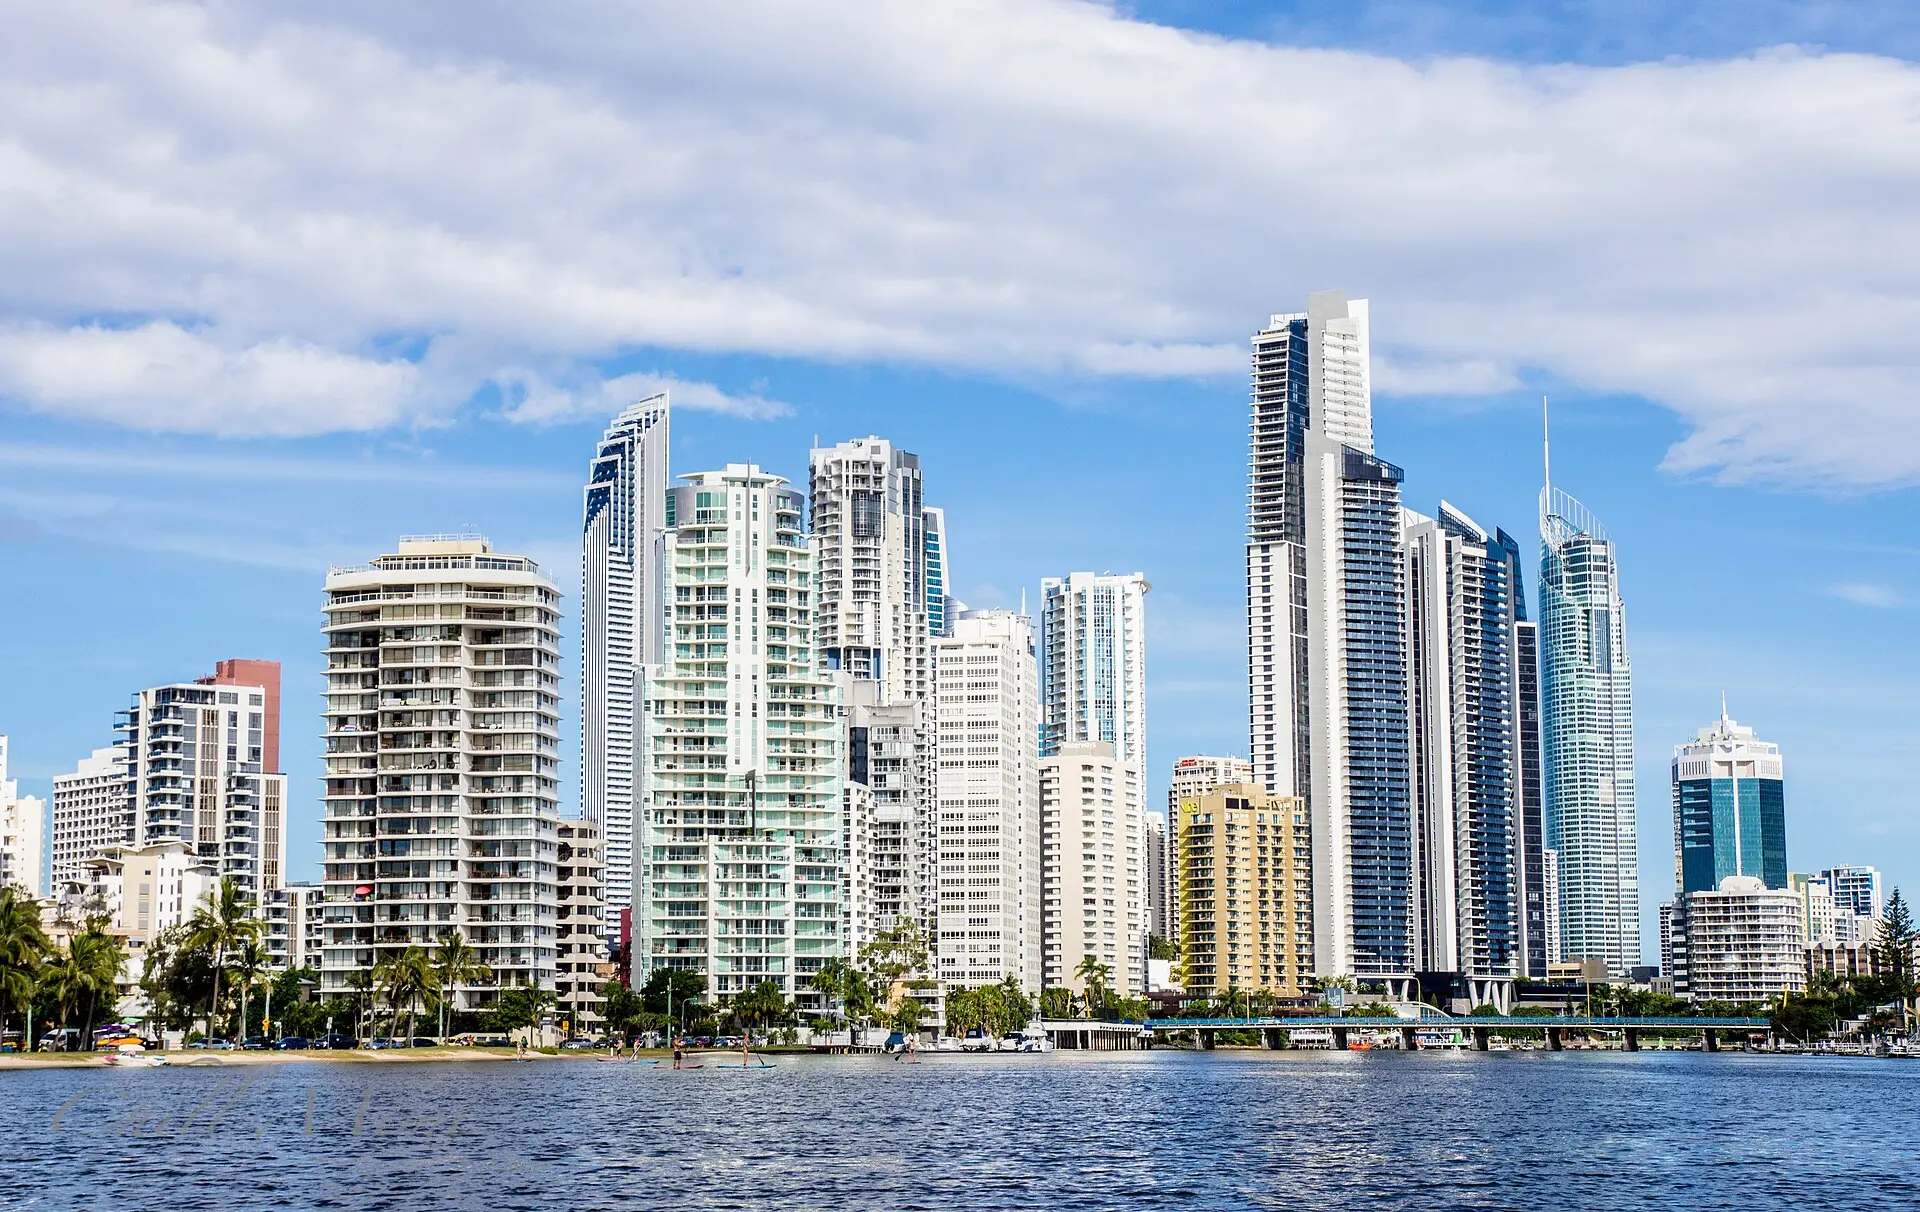
The Gold Coast has a distinctive mix: high-rise apartments along the beachfront, canal-front homes, newer estates in the northern growth corridor, hinterland acreage and industrial estates near the M1. Each is assessed on its own evidence. Apartments in particular vary widely by building, aspect and body corporate health, so recent resales in the same complex are the most useful evidence. No valuation is needed before approval.
See what your Gold Coast property can support with a short enquiry.
Queensland specifics
Gold Coast titles sit on the Queensland register, so any mortgage or caveat is lodged through Titles Queensland. Purchases attract duty collected by the Queensland Revenue Office, and building contractors operate under QBCC licensing.
Development cycles on the Gold Coast
Apartment development on the Gold Coast tends to move in cycles, with periods of heavy supply followed by slower absorption. Developers who complete projects during a softer period can find themselves with unsold stock when construction loans mature. A residual stock loan lets them hold and sell at sensible prices rather than discount heavily. Planning for that possibility before completion is far better than reacting afterwards.
An illustrative Gold Coast loan
Illustrative only. A developer completes a boutique apartment building in Burleigh. Most units settle, but four remain unsold when the construction loan is due. A residual stock loan over the four units repays the construction lender, with interest capitalised. The developer relists the units with a new campaign and sells them over the following six months, each settlement reducing the loan until it is cleared.
Questions Gold Coast owners ask
Can short-stay apartments be used as security? Yes, assessed as residential property with the use and building rules noted.
Can a Gold Coast property fund a business in Brisbane or interstate? Yes. The security and the business can be in different places.
Do flood overlays matter? Yes, as part of the property assessment, alongside insurance availability.
Mistakes to avoid
- relying on peak-season trading to repay without a buffer
- completing a development without a plan for unsold stock
- underestimating body corporate levies on held apartments
- using tax money to fund refurbishments
The Gold Coast’s property mix in detail
The northern growth corridor around Coomera, Pimpama and Ormeau has added large numbers of new homes, assessed on estate-level sales. Central suburbs such as Southport, Broadbeach and Surfers Paradise are dominated by apartments and commercial buildings. The southern beaches from Burleigh to Coolangatta command strong prices for both houses and apartments, while the hinterland offers acreage and lifestyle properties with a smaller buyer pool. Industrial estates around Yatala, Molendinar and Burleigh serve trades, manufacturing and logistics businesses.
Tourism seasonality and events
Hospitality and tourism businesses on the Gold Coast see strong peaks during school holidays, major events and the winter escape season for southern visitors. Funding a refurbishment or new venture ahead of those peaks, with interest capitalised, lets the business capture the busy period before repayments are due. A buffer in the term protects against a softer season.
Builders in a busy market
Strong population growth has kept Gold Coast builders and trades busy, but busy does not always mean liquid. Progress claims, retentions and slow-paying head contractors create gaps that a secured loan behind a home or yard can bridge. See construction.
Gold Coast property, realistic terms
Whether you own a beachfront apartment, a canal home or a warehouse in an industrial estate, the process is the same. A short note on the property, any existing loan, the amount and the exit is enough to start. No credit check applies to a first enquiry, and your details stay within our team, and recent sales in your building or street help us respond quickly. Start a Gold Coast enquiry.
Frequently asked questions
Can a Gold Coast apartment secure a business loan?
Yes. Apartments are assessed on the building, unit size, view, body corporate and recent resales in the complex and area.
Do you lend to Gold Coast developers?
Yes. Site acquisitions, holding finance and residual stock loans are common on the Gold Coast.
Can a canal-front home be used as security?
Yes. Waterfront homes are assessed on local sales evidence like any other property.
Do you lend in the hinterland?
Yes, case by case, with acreage and lifestyle properties assessed on local evidence.
Prefer to start now? Enquire here
About 60 seconds. No credit check when you first enquire, and a secured lending specialist calls you back.