Quick answer
Sunshine Coast business owners use property-secured loans to fund tourism and hospitality, construction and trades, development projects and property purchases, often using equity built up in coastal and hinterland homes. Loans run from $20,000 to $5,000,000 as first mortgages, second mortgages or caveats, with titles handled by Titles Queensland and no valuation needed before approval.
Key points
- Lending from Caloundra to Noosa and across the hinterland
- Strong equity growth in many coastal homes
- Tourism, hospitality, construction and development businesses commonly funded
- Titles Queensland handles registrations and caveats
- Interest can be prepaid or added to the loan
A fast-growing region with strong equity
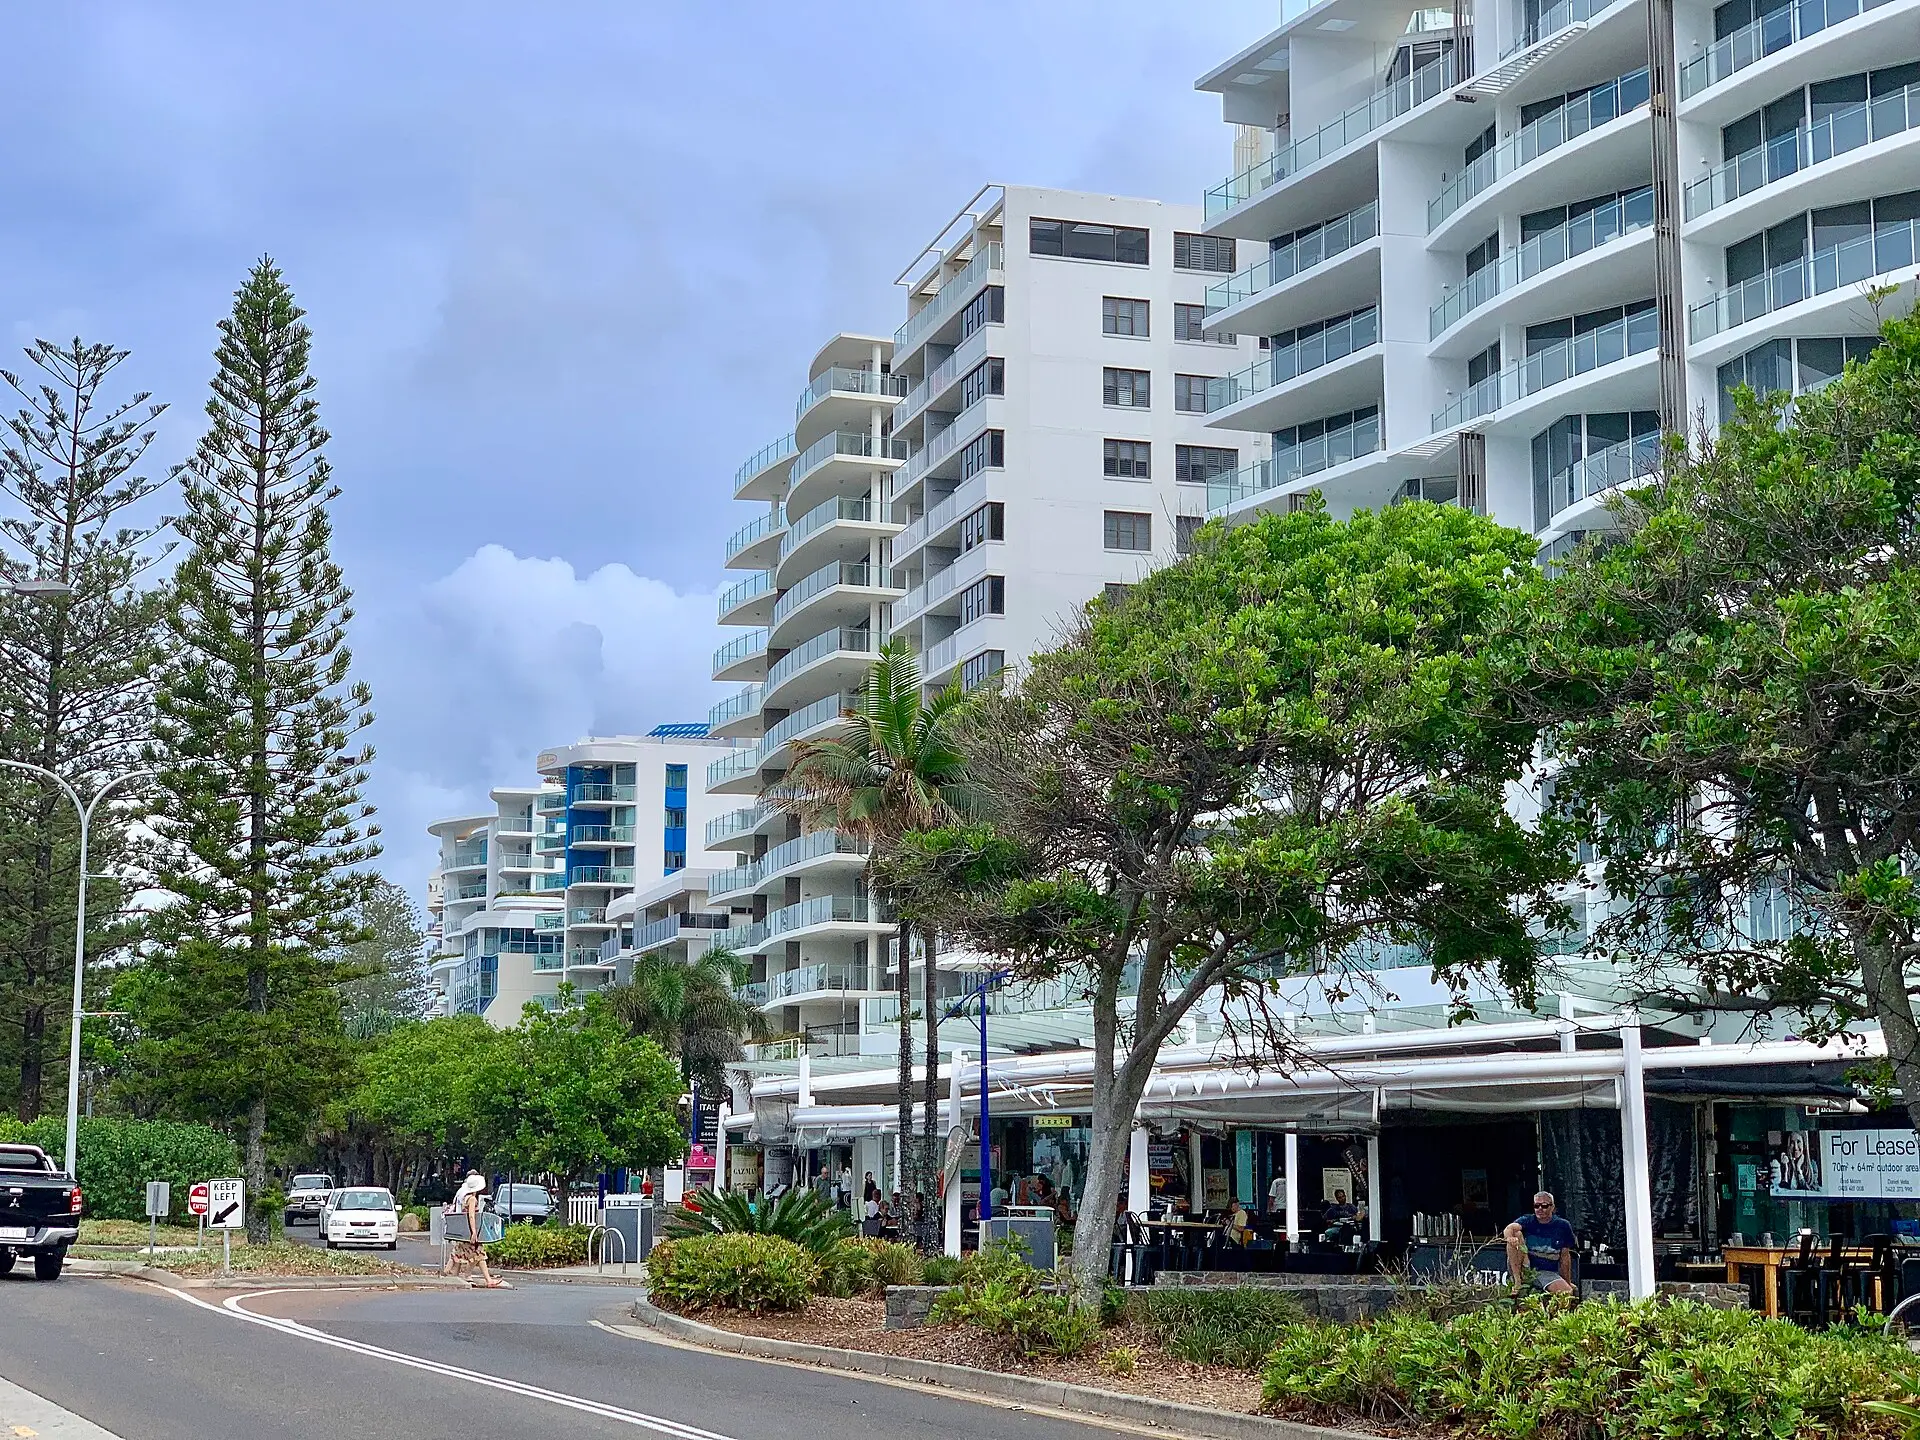
The Sunshine Coast has been one of Australia’s fastest-growing regions, attracting families, retirees and businesses relocating from the capitals. Population growth has supported construction, health care, retail and tourism, while property values in many coastal suburbs have risen substantially. For long-term owners, that growth means significant equity, often far more than their bank loan reflects. A secured loan can put that equity to work for the business without disturbing the existing mortgage.
How Sunshine Coast businesses use secured finance
- Construction and trades. Bridging progress claims and retentions during a building boom. See trades.
- Tourism and hospitality. Refurbishing venues and accommodation in Mooloolaba, Noosa and Coolum, and carrying businesses through quieter months.
- Development. Buying sites, holding through approvals and carrying completed townhouse or apartment stock.
- Relocating businesses. Buying premises for a business moving from Brisbane or interstate.
- Equity release. Funding growth from a home with plenty of equity behind a modest loan. See equity release.
The Sunshine Coast property mix
The region spans beachside suburbs from Caloundra through Mooloolaba and Maroochydore to Noosa, newer master-planned communities, hinterland towns such as Maleny and Montville, and industrial areas around Kunda Park, Caloundra West and Noosaville. Beachside and Noosa properties command premium prices, while hinterland acreage and lifestyle properties have smaller buyer pools. Each property is assessed on its own recent sales evidence. No valuation is needed before approval.
See what your Sunshine Coast property can support with a short enquiry.
Queensland specifics
On the Sunshine Coast, security interests are lodged on the Queensland title register maintained by Titles Queensland, and duty on a purchase is assessed by the Queensland Revenue Office. Construction businesses should remember that their QBCC licence carries financial requirements that new debt can affect.
The new city centre and infrastructure
Major investment in the Maroochydore city centre, health precincts and transport infrastructure has supported commercial property demand and created work for local businesses. Contractors and suppliers to these projects face the same milestone payment patterns as anywhere else, and property-secured loans help them carry the gap between costs and payment.
An illustrative Sunshine Coast loan
Illustrative only. A carpentry business based in Kunda Park has grown to a crew of twelve working for several builders. Two builders have stretched payment terms during a busy period, and the business has fallen behind on BAS. The owner’s Buderim home carries a small bank loan. A second mortgage behind the bank clears the ATO and funds wages and materials for two months, with interest capitalised. As claims are paid, the loan is reduced and then cleared.
Seasonal tourism
Tourism-dependent businesses see strong peaks in school holidays and over summer, with quieter periods in between. Borrowing before the quiet months, with interest capitalised, lets a business keep staff and prepare for the next peak. A buffer in the term protects against a weaker season or an event such as severe weather.
Questions Sunshine Coast owners ask
Can acreage in the hinterland be used? Yes, case by case, with local evidence and sometimes additional security.
Can I buy commercial premises for a business relocating from Brisbane? Yes. A private loan can settle the purchase quickly, with a bank refinance once the business is established locally.
How quickly can a loan settle? On straightforward deals, in as little as 24 hours once documents are signed.
Mistakes to avoid
- relying on peak-season trading without a buffer
- using GST and PAYG withholding to cover wages during a building boom
- assuming acreage will be valued like a suburban house
- leaving development finance until the construction loan matures
Health, education and professional services
The growth of the region’s health and university precincts has created demand for medical suites, allied health clinics and professional offices. Practitioners buying their rooms or fitting out new premises often use a private loan to settle on time and refinance with a bank later. See medical and dental practices for how those deals are usually structured.
Businesses relocating to the coast
Many owners move their businesses, or open second locations, on the Sunshine Coast. A private loan secured over property in Brisbane or interstate can fund premises, fit-out and working capital while the business establishes itself locally, with a bank refinance once it has local trading history.
Sunshine Coast property, practical finance
From a Noosa apartment to a Caloundra warehouse, each property is judged on its own facts. Outline the security, the debt against it, the purpose and the planned repayment. A first enquiry carries no credit check, and your details stay with one team, and recent local sales help us respond quickly and accurately. Start a Sunshine Coast enquiry.
Frequently asked questions
Do you lend in Noosa and the hinterland?
Yes. Coastal towns, hinterland villages and acreage properties are all considered, each assessed on local sales evidence.
Can a Sunshine Coast home fund a business elsewhere?
Yes. The property can be on the Sunshine Coast while the business operates anywhere in Australia, provided the loan is for business purposes.
Do you lend to builders on the Sunshine Coast?
Yes. Builders and trades often use property-secured loans to bridge progress payments on the region's busy residential projects.
Can holiday rental properties be used as security?
Yes. Holiday and short-stay properties are assessed as residential property on local evidence, with their use noted.
Prefer to start now? Enquire here
About 60 seconds. No credit check when you first enquire, and a secured lending specialist calls you back.